Neighborhood Housing Services of Greater Berks, Inc. is a non-profit housing organization located at 213 N 5th St #1030 in Reading, Pennsylvania. The organization works in the field of affordable homeownership, providing housing counseling, homebuyer education, lending assistance and related support services to residents of Reading and the surrounding Berks County area. It can be reached by phone at +1 610-372-8433.
The agency operates in the tradition of neighborhood housing services organizations across the United States, which were established to help working households buy, repair and keep their homes in communities where conventional financing and down payment resources were historically difficult to access. In practical terms, that means the staff spends much of its time on two tasks: teaching people what the home buying process actually involves, and helping them assemble the financial pieces needed to complete a purchase.
Housing Counseling
One-on-one counseling is a central part of the organization's work. Counselors meet with prospective buyers to review income, debt, savings and credit history, then outline what needs to happen before a mortgage application is realistic. Sessions typically cover budgeting, credit repair strategies, debt-to-income calculations, what lenders look for in an application and how much house a given household can reasonably afford. For many clients, this is the first time someone has walked through the numbers line by line and explained what each one means.
Counseling is not limited to people who are ready to buy immediately. Clients who need a year or more of preparation work with counselors to set goals, track progress and return for follow-up sessions. This longer arc of service is one of the distinguishing features of non-profit housing counseling compared with a transactional relationship at a bank or brokerage.
Services are provided in both English and Spanish, which matters in Reading, a city with a large Spanish-speaking population. Having counselors who can explain mortgage terminology, closing documents and loan conditions in a client's first language removes a significant barrier for many households.
Homebuyer Education Classes
The organization runs homebuyer education courses that cover the full arc of a purchase, from the initial decision to buy through closing and the responsibilities that follow. Typical subject matter includes:
- Assessing readiness to buy and comparing renting with owning
- Credit reports, credit scores and how to improve them
- Budgeting for a down payment, closing costs and reserves
- Mortgage products, interest rates, escrow and private mortgage insurance
- Working with real estate agents and making an offer
- Home inspections, appraisals and title work
- What happens at settlement and what documents are signed
- Property taxes, homeowners insurance and ongoing maintenance costs
- Avoiding predatory lending and recognizing common scams
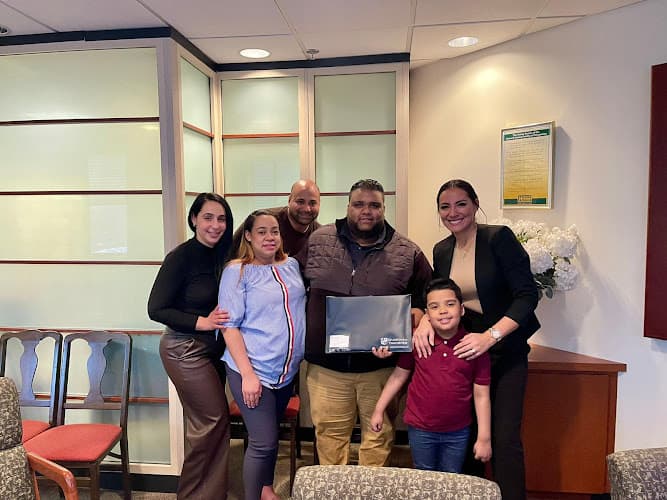
Completion of a certified homebuyer education course is a requirement for many down payment assistance programs and for certain first-time buyer mortgage products, including programs administered through state and federal housing agencies. The certificate issued at the end of the course is often the document a lender asks for. Classes are led by staff presenters and are generally structured to allow questions throughout rather than running as a lecture.
Down Payment and Closing Cost Assistance
For many buyers in Berks County, the obstacle is not monthly affordability but the cash needed at closing. The organization administers and connects clients to down payment assistance and closing cost programs, including grants and secondary financing, that reduce the amount a buyer must bring to settlement. These resources allow households to purchase without depleting savings entirely, leaving a cushion for repairs, moving expenses and emergencies.
Eligibility for assistance programs generally depends on household income, purchase price, property location, occupancy as a primary residence and completion of homebuyer education. Because program rules and funding availability change, prospective applicants are encouraged to call the office to confirm current requirements before making plans around a particular source of funds. Real estate agents and loan officers working with buyers in the area also coordinate with the organization when a transaction needs assistance to come together.
Lending and Related Services
In addition to counseling and education, the organization has a lending function that works with applicants on qualification and loan processing. Staff handle document collection, verification and the back and forth with underwriting that borrowers often find confusing. The organization also addresses housing issues beyond purchase, including guidance for existing homeowners on repairs, foreclosure prevention and maintaining property in Reading's older housing stock. Much of the city's housing was built in the late nineteenth and early twentieth centuries, and rowhome ownership comes with its own set of structural, mechanical and code considerations.
Location and Access
The office sits on North Fifth Street in downtown Reading, within the central business district and near the city's government and commercial corridor. The location is reachable by local bus service and is close to parking in the downtown area. Accessibility features include a wheelchair accessible entrance, wheelchair accessible seating, a wheelchair accessible restroom and a wheelchair accessible parking lot.
The organization identifies as Latino-owned and veteran-owned, and is listed as LGBTQ+ friendly and a transgender safe space. Its service area centers on the City of Reading and extends across greater Berks County, including surrounding boroughs and townships.
Practical Information
Appointments are the usual way to begin, and calling the office at +1 610-372-8433 is the direct route to scheduling a counseling session or registering for a class. Clients preparing for a first appointment generally find it useful to bring recent pay stubs, the two most recent federal tax returns and W-2 forms, recent bank statements, a list of monthly debts and a government issued photo identification. Having these documents in hand allows a counselor to give specific figures rather than general guidance during the first meeting.
Because the organization is a non-profit, its services are structured around mission rather than commission, and counselors are not working on behalf of a particular lender or seller. That independence is part of why real estate professionals, employers and community groups in Berks County refer first-time buyers to the agency. For households that have never navigated a mortgage application, inherited no family experience with the process, or are working through credit or language barriers, the combination of classroom instruction, individual counseling and access to assistance funds is designed to function as a single pathway from renting to ownership.