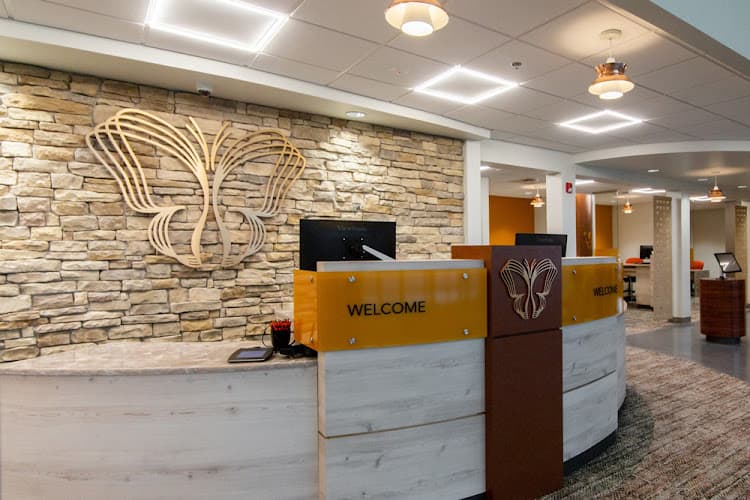
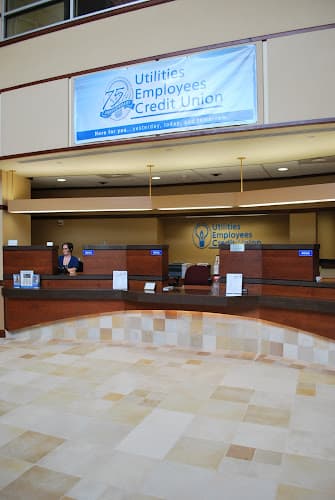
Discovery Federal Credit Union is a member-owned financial cooperative located at 2744 Century Blvd in Wyomissing, Pennsylvania, just off the commercial corridor that serves western Berks County. Like all federally chartered credit unions, it operates as a not-for-profit institution owned by the people who bank there rather than by outside shareholders. Earnings are returned to members in the form of deposit rates, loan pricing and services instead of being distributed as profit, which is the structural difference that most often separates a credit union from a commercial bank.
The Century Boulevard office functions as a full-service branch, handling everyday deposits and withdrawals, account openings, loan applications, certificates and consultations with lending staff. The credit union can be reached by phone at +1 610-372-8010.
Membership and Structure
Credit unions serve a defined field of membership, and joining typically involves opening a share account that represents an ownership stake in the cooperative. That share account is the foundation for everything else, from checking and savings to loans and certificates. Members elect a volunteer board of directors drawn from the membership itself, which means governance decisions are made by people who use the institution rather than by a distant corporate office.
Deposits at federal credit unions are insured by the National Credit Union Share Insurance Fund, administered by the National Credit Union Administration, an agency of the United States government. The coverage operates in much the same way as deposit insurance at a bank, protecting member accounts up to the limits set by federal regulation.
Deposit Accounts and Savings Products
Day-to-day banking products at Discovery Federal Credit Union generally include share savings accounts, checking accounts with debit card access, and certificate accounts for members who want to set money aside for a fixed term at a stated rate. Certificates, sometimes called share certificates, work in a similar fashion to bank certificates of deposit, with a range of terms available so that members can match the maturity to their own plans. Staff at the branch regularly walk members through the differences between terms and explain how dividends are earned and credited before an account is opened.
Other common credit union deposit services include direct deposit setup, automatic transfers between accounts, and club or goal-based savings accounts for holidays, vacations or tax obligations. Members who route a paycheck through direct deposit sometimes qualify for additional benefits on other products, a practice that is common across the credit union sector and one that the lending staff can explain in detail during a consultation.
Lending Services
Lending is a significant part of what the credit union does. Typical offerings at an institution of this type include new and used auto loans, personal loans, home equity loans and lines of credit, credit cards and refinancing of loans originated elsewhere. Borrowers who come in with financing already arranged through a car dealership often ask the credit union to review the terms, since a cooperative lender can sometimes restructure the arrangement on different terms.
Ancillary protection products associated with vehicle lending, including guaranteed asset protection coverage, are also part of the picture. Guaranteed asset protection, usually shortened to gap coverage, addresses the difference between what an insurer pays after a total loss and the balance still owed on the loan. Credit unions commonly price this coverage differently from dealership finance offices, and members are encouraged to compare before signing paperwork at a dealer.
Loan interviews at the branch are typically conducted at a desk or cubicle rather than at a teller window, allowing a loan officer to review credit, discuss term length and monthly payment tradeoffs, and outline the documents required for underwriting. Home equity borrowing in particular involves additional steps such as valuation and title work, and the staff handling these files walk applicants through the sequence and the expected timeline.
The Branch and Visiting in Person
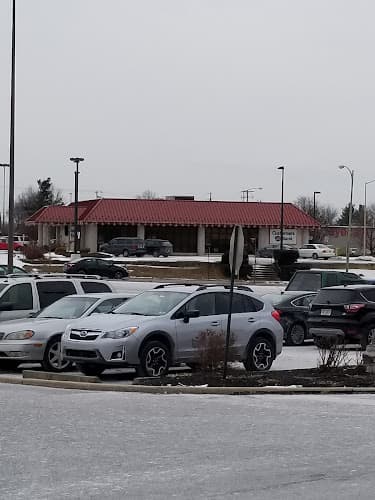
The Wyomissing office includes a drive-through lane for routine transactions such as deposits, withdrawals and loan payments, which is useful for members who want to handle banking without leaving the car. Onsite services are available for members who come inside, and cash advance transactions can be processed at the branch.
Accessibility features include a wheelchair accessible entrance and a wheelchair accessible parking lot, so members using mobility devices can reach the lobby without navigating steps or curbs. Parking is on site. Century Boulevard sits in a part of Wyomissing that is reachable from Route 422 and the Broadcasting Road area, placing the branch within a short drive of Reading, Sinking Spring, Shillington, West Lawn and the surrounding townships of Berks County.
Digital and Remote Banking
Members can open accounts and manage balances electronically in addition to visiting the branch. Online and mobile banking generally cover balance inquiries, transaction history, transfers between accounts, bill payment, mobile check deposit and card controls. Account applications can be started remotely, with identity verification and funding handled as part of the enrollment process. Members who prefer to combine the two approaches often open an account online and then visit the branch when a question calls for a longer conversation.
Practical Information
- Address: 2744 Century Blvd, Wyomissing, PA 19610
- Phone: +1 610-372-8010
- Type: Federally insured, member-owned credit union
- Branch features: drive-through lane, onsite services, cash advance
- Accessibility: wheelchair accessible entrance and parking lot
- Service area: Wyomissing, Reading and surrounding Berks County communities
Prospective members are advised to call ahead to confirm current branch hours, to ask about eligibility for membership, and to find out which documents to bring when opening an account or applying for a loan. For auto, personal and home equity borrowing, having income documentation and details about the purchase or property on hand at the first appointment usually shortens the overall process. Questions about rates, terms and product availability are best directed to the branch by phone, where staff can give answers specific to a member's situation.