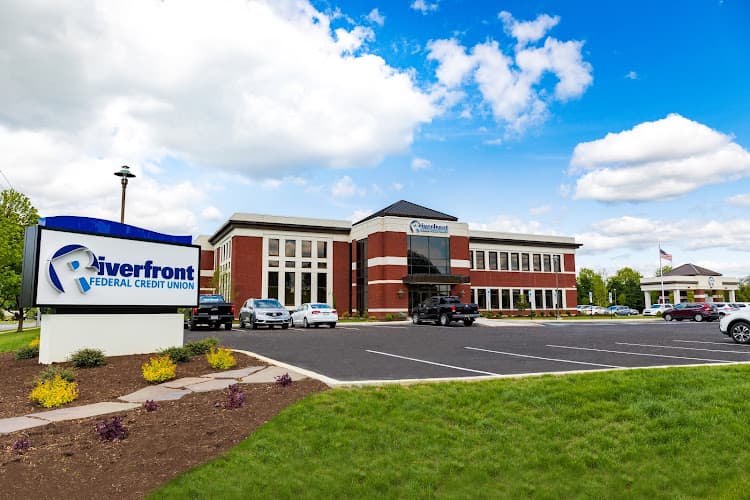
First Commonwealth Federal Credit Union operates a branch at 609 Spring St in Wyomissing, Pennsylvania, serving members in Berks County and the surrounding region. As a federally chartered credit union, it is a member-owned, not-for-profit financial cooperative rather than a shareholder-owned bank. That structure shapes how the organization works: people who open accounts become members with an ownership stake, and earnings are returned to the membership in the form of deposit rates, loan pricing, and account features instead of being distributed to outside investors.
Credit unions in Pennsylvania generally serve a defined field of membership, which can include residents of particular counties, employees of partner organizations, and family members of existing members. First Commonwealth has grown from its origins in the Lehigh Valley into a broader eastern Pennsylvania presence, with the Wyomissing office extending that network into the Reading area. Members who join at one branch can typically conduct business at any location, and shared branching arrangements common among credit unions often allow transactions at cooperating institutions in other parts of the country.
Accounts and Everyday Banking
The credit union handles the full range of consumer deposit products. These generally include checking and savings accounts, money market accounts, certificates, youth and student accounts, and retirement savings options such as individual retirement accounts. Among the checking products, the Kasasa line is the one members mention most often. Kasasa is a nationally licensed reward checking program used by community banks and credit unions, and it typically pays cash back or higher dividends to account holders who meet monthly qualifications such as a minimum number of debit card purchases, enrollment in electronic statements, and direct deposit or automatic payments. Many versions of the program also refund ATM surcharges incurred at machines outside the institution's own network, which can matter to members who travel or who live some distance from a branch.
Debit and credit cards are issued through the credit union, with contactless payment and digital wallet support available for everyday purchases. Card controls, transaction alerts, and fraud monitoring are part of the standard account toolkit, allowing members to freeze a card temporarily, receive notifications about unusual activity, and confirm or decline flagged transactions.
Lending
Lending is a substantial part of the credit union's business. Typical offerings include:
- New and used vehicle loans, including refinancing of auto loans originated elsewhere
- Personal and unsecured loans, as well as debt consolidation
- Home equity loans and home equity lines of credit
- First mortgages, refinancing, and related residential real estate lending
- Credit cards
- Recreational vehicle, motorcycle, and boat financing
- Business lending and commercial deposit services for small and mid-sized employers
Auto lending and refinancing are frequent reasons members visit a branch in person. Staff at the Wyomissing office work with borrowers on rate comparisons, term selection, and the paperwork involved in retitling a refinanced vehicle. Home equity borrowing is another common conversation, particularly for homeowners funding renovations or consolidating higher-rate balances. Because loan decisions are made within a member-owned institution, applicants often deal with the same office from application through closing rather than being routed to a distant processing center.
Digital and Mobile Banking
Online and mobile banking cover the routine tasks that most members handle without visiting a branch: balance checks, transaction history, transfers between accounts, bill payment, person to person transfers, and card management. The mobile application supports digital wallet enrollment so that cards can be loaded onto a phone or watch for tap payments at checkout. Real time posting of transactions is a feature members notice, since it allows spending to be tracked through the day rather than at the end of a statement cycle.
Alerts can be configured for low balances, large purchases, and suspicious activity. If a card is misplaced, members can disable it from the app and re-enable it once it turns up, which avoids the inconvenience of a full replacement for a card that was simply left in a jacket pocket.
The Wyomissing Branch
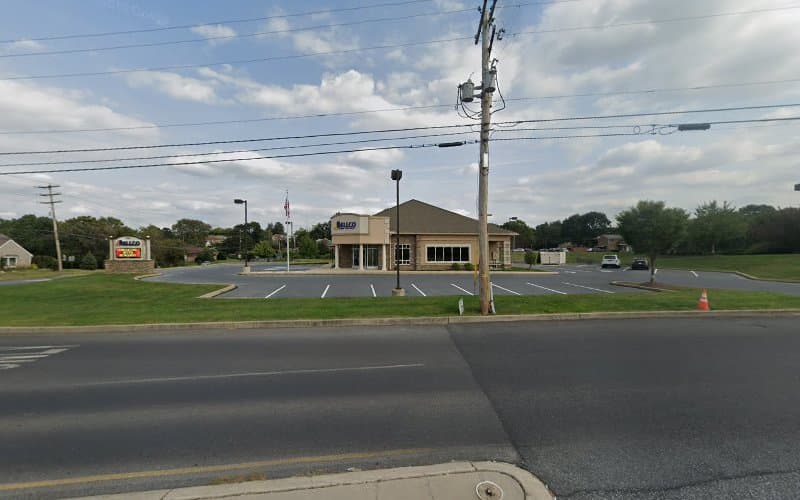
The Spring Street location sits in a commercial corridor in Wyomissing, convenient to surrounding Berks County communities including West Reading, Reading, Shillington, Sinking Spring, and Spring Township. The branch is equipped with a drive-through, which handles deposits, withdrawals, loan payments, and similar teller transactions without leaving the vehicle. This is useful during inclement weather and for members running errands with children or passengers in the car.
Accessibility features include a wheelchair accessible entrance and a wheelchair accessible parking lot, so members using mobility devices can reach the lobby and teller area directly from designated parking. Inside, staff handle account openings, loan applications and closings, certificate purchases, notary and signature guarantee requests where available, and questions about online banking enrollment.
The main telephone line is +1 888-821-2400. Calling ahead is a practical step for anything that requires documentation, such as a loan closing, a business account opening, or an estate or trust matter, since bringing the right identification and paperwork on the first visit shortens the appointment considerably.
What to Bring and How to Join
Opening a membership generally requires government issued photo identification, a Social Security number or taxpayer identification number, proof of address, and a small opening deposit that establishes the member's share in the cooperative. Applicants should also be prepared to confirm eligibility, which is usually based on where they live or work or on a family relationship to an existing member. For loan applications, income documentation such as recent pay stubs or tax returns, information on existing debts, and details about the collateral, including a vehicle identification number or a property address, will speed the process.
Why Members Choose a Credit Union
Deposits at federally insured credit unions are protected by the National Credit Union Share Insurance Fund, administered by the National Credit Union Administration, with coverage limits comparable to federal deposit insurance at banks. Beyond insurance parity, the appeal for many members is the combination of competitive loan rates, reward based checking, and the ability to speak with lending and service staff who work in the same branch they walk into. For Berks County residents who want those features without driving out of the area, the Wyomissing office provides a local point of contact for an institution whose reach extends across eastern Pennsylvania.