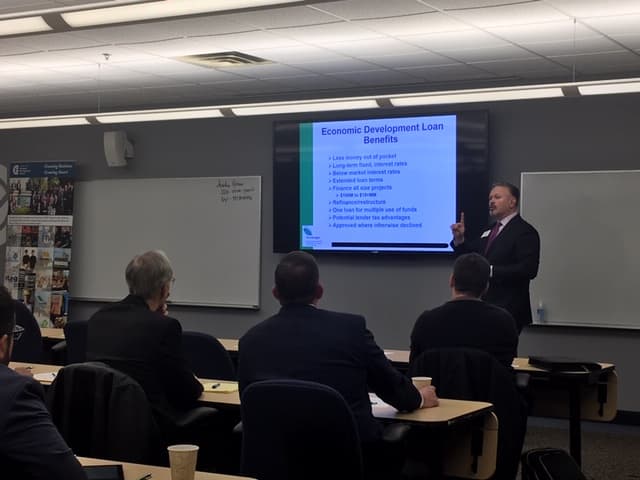
South Eastern Economic Development Company of Pennsylvania, known professionally as Seedcopa, is an economic development organization based in Exton, Chester County. The company operates as a Certified Development Company (CDC), a designation granted by the U.S. Small Business Administration to nonprofit organizations authorized to originate, process, close, and service SBA 504 loans. In practical terms, this means Seedcopa is one of the entities through which small businesses in the region access long term, fixed rate financing for real estate and major equipment purchases that conventional bank lending alone may not cover.
CDCs occupy an unusual position in the lending landscape. They are mission driven organizations measured in part by the economic activity they help generate: jobs created and retained, commercial properties brought back into productive use, and small companies given the capital structure to grow past the point where leased space or aging equipment becomes a constraint. Seedcopa's work sits at the intersection of banking, government program administration, and regional economic development, and its staff function as intermediaries between borrowers, participating lenders, and the SBA itself.
How the SBA 504 Program Works
The 504 loan is structured differently from a standard commercial mortgage. Rather than a single loan from a single source, a typical 504 project is financed in three parts. A conventional lender, usually a bank or credit union, provides a first mortgage covering roughly half of the total project cost. The CDC provides a second position loan funded through a debenture guaranteed by the SBA, generally covering up to 40 percent. The borrower contributes the remaining equity, often around 10 percent, though startups and special purpose properties typically require more.
The appeal of this structure for small business owners is twofold. The lower equity requirement preserves working capital that would otherwise be tied up in a down payment, and the CDC portion carries a fixed interest rate over a long term, commonly 10, 20, or 25 years depending on the assets financed. Because the debenture rate is set at the time of the monthly bond sale rather than negotiated individually, borrowers of all sizes receive comparable pricing. For a company that has been carrying variable rate debt, converting to a fixed rate instrument can materially change its cost of capital and make long range planning more predictable.
Eligible Projects and Uses of Funds
The 504 program is designed for fixed assets rather than general operating needs. Common uses include:
- Purchase of existing owner occupied commercial buildings, including office, industrial, retail, and medical properties
- Ground up construction of a new facility
- Purchase of land and site improvements such as grading, parking lots, utilities, and landscaping
- Renovation, expansion, or modernization of a building the business already owns
- Acquisition of heavy machinery and equipment with a useful life of at least 10 years
- Soft costs associated with a project, including certain professional fees, appraisals, environmental reports, and interim interest
Owner occupancy rules apply. A business buying an existing building generally must occupy at least 51 percent of the space, while new construction typically requires occupancy of 60 percent initially with a plan to occupy more over time. This allows a growing company to acquire a property larger than its current footprint and lease the balance until it is needed.
Refinancing Existing Debt
Beyond acquisition and construction financing, the 504 program includes provisions for refinancing qualifying commercial debt, with or without an expansion component. Businesses that financed a property years ago with a balloon note, a shorter amortization, or a floating rate may be candidates to move that obligation into a longer term, fixed rate structure. In some circumstances, eligible business expenses can also be addressed as part of a refinance. The rules governing these transactions have been revised several times since the program's introduction, so eligibility is best confirmed directly with the CDC based on current SBA guidance.
Eligibility Considerations
SBA 504 financing is aimed at for profit small businesses operating in the United States. Size standards are based on tangible net worth and average net income rather than employee count alone, and the thresholds are set generously enough that many established companies still qualify. Projects are also expected to advance a public policy or economic development objective, most commonly job creation or retention measured against the amount of SBA funding requested, though alternatives exist for manufacturers, rural businesses, veteran owned firms, energy efficiency projects, and several other categories. Certain business types, including passive real estate holding companies and speculative development, are excluded, although a common and permitted arrangement is for an operating company to lease its facility from a related holding entity.
The Process and the CDC's Role
A 504 transaction involves more moving parts than a conventional loan, which is where the CDC's function becomes most visible. Seedcopa's staff coordinate with the participating first mortgage lender, assemble the application package for SBA review, track appraisals, environmental assessments, title work, and construction documentation, and manage the timing of the debenture funding, which occurs on a monthly cycle. During construction projects, interim financing is typically provided by the bank and taken out by the debenture once the project is complete. Because the sequence and the paperwork are unfamiliar to most first time borrowers, much of the CDC's practical value lies in project management and in translating SBA requirements into concrete next steps.
Seedcopa also works alongside other public financing tools. Businesses in Pennsylvania may be able to combine SBA financing with state and local programs, and the organization's economic development orientation means staff are generally familiar with what else may be available for a given project or location.
Location and Visiting
Seedcopa is located at 737 Constitution Drive, Suite 1100, in Exton, Pennsylvania, within the Route 30 business corridor in central Chester County. The site is convenient to the Pennsylvania Turnpike and Route 202, placing it within reasonable driving distance of Philadelphia, Wilmington, Lancaster, and the Lehigh Valley. The building offers a wheelchair accessible entrance and a wheelchair accessible parking lot.
The office can be reached by telephone at +1 610-458-5700. Prospective borrowers often begin the conversation before they have selected a property or a bank, since understanding the equity requirement and project structure early can shape what is realistic. Businesses already working with a lender can ask that lender to bring Seedcopa into the discussion as the CDC partner on the transaction.