How to Choose an Insurance Agent in Berks County
Every Pennsylvania agent holds the same license. What separates them is six questions, what they do at renewal, and how they handle a switch. Ask these.
If you're wondering how to choose an insurance agent, start here: every agent in Pennsylvania holds the same state license, so the license isn't what separates a good one from the rest. What separates them is how they answer six plain questions in the first conversation, and what they do for you the day your renewal comes in higher. Pick two agents from our Berks County insurance agents page, check both on the state lookup in about a minute, and ask.
Every insurance agent in Pennsylvania holds the same license, and you can check it in a minute.
The state's name for an agent's license is "insurance producer," and it's the same license whether the agent sells for one company or twenty. Keeping it means at least 24 hours of continuing education every two years, so "licensed" is the floor everyone stands on.
The lookup shows more than whether the license is valid. The Pennsylvania Insurance Department's Licensed Individual Search needs only the agent's last name or city, and it lists the types of insurance the agent can offer and the companies they're authorized to work with. There's a matching search for the agency itself, and a Regulatory and Enforcement Action Search that lists any corrective action the Department has taken against a licensee. If you want the click-by-click version, we wrote a step-by-step license lookup.
Independent vs captive agent: the difference shows up at renewal.
An independent agent sells policies from many different companies. A captive agent sells for one. Both are paid a commission by the insurer for the sale, so the question isn't who's on your side. It's what happens the year your rate moves.
The renewal belongs to the independent agency, not to the insurer. If your current company's price jumps, the renewal is the agency's to place with another of the companies it sells for, and you keep the same agent. We cover the whole split in our post on independent vs captive agents in Berks County.
What Berks County customers praise in an insurance agent.
The state's advice is that cost is one thing to research but not the only one: how the customer service is, whether the coverage is adequate, whether the agent has a complaint history. So we counted what Berks County customers say when they're happy, from the positive review themes on every active insurance agent listing in our directory.
| What Berks customers praise in an insurance agent | Share of Berks agents whose reviews praise it |
|---|---|
| Friendly, personal, professional service | 95 percent |
| Responsiveness and communication | 86 percent |
| Knowledge, and explaining coverage plainly | 74 percent |
| Pricing, value and savings | 67 percent |
| Trust and a long relationship | 49 percent |
| Help with a claim | 17 percent |
Counted September 18, 2026 from the review themes on active Berks County insurance agent listings that carry review themes; an agency counts in every row its reviews praise, so the rows overlap.
First comes friendly, personal and professional service, on nine in ten listings. Second, on nearly nine in ten, is responsiveness and communication: the agent answered. Third is knowledge and explaining coverage plainly. Fourth is pricing, value and savings. Fifth is trust and a long relationship. Last, on fewer than one listing in five, is help with a claim, the moment the whole thing is for. So ask about claims on purpose.
The specific compliments repeat, too. "Quick" or "fast" shows up on about half the listings, and so does some version of "answered the phone" or "got back to me." "Saved me money" is on a little under half, "easy" on about four in ten, and "explained things" and "been with them for years" each on roughly one in four.
The "explained things" compliment looks like this on one listing. DJI Insurance Agency in Kutztown has a review describing the agent sitting down at the customer's home twice to go over the policies and revisions, and another saying they got better quality coverage for the same money.
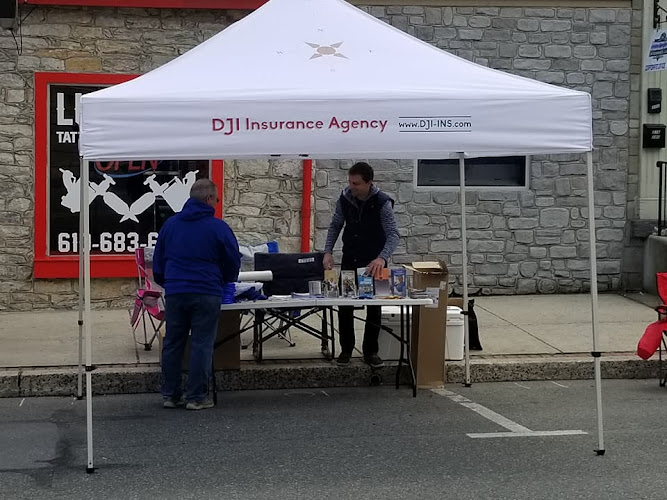
600 Noble St Suite 220, Kutztown, PA
The six questions to ask an insurance agent before you switch.
Ask these six in one conversation with each agent and listen to how they're answered. The state's advice is to compare at least three companies, and an independent agent may sell for many, so ask each agent how many companies they'd quote you. Pull your two names from our Berks County insurance agents page, where the county's agencies are listed and each profile shows its review themes.
1. Which companies are you appointed with? Appointed means authorized to sell for. Check the answer against the lookup you already ran.
2. How are you paid on this policy, and is there any fee? On a home or car policy, expect "commission," paid by the insurer, and no fee. Pennsylvania allows a fee on top of commission only for business insurance, and never for filling out an application. The one exception is a broker, someone you hire to shop for you and who is generally paid by you, and that takes a signed written agreement spelling out the fee before they do anything. If you hear the word fee on a personal policy, ask for the paper.
3. If my rate moves at renewal, what can you do about it? An independent agent should be able to name the companies they'd shop you to. A captive agent should be able to say what their company can do within the policy. Either answer is fine as long as it's specific.
4. Full tort or limited tort, and what does each cost me? Your car renewal offers two options. With limited tort, if another driver injures you or someone in your household, you can claim medical bills and other out-of-pocket costs, but not pain and suffering. You can still claim pain and suffering if the injury is serious, or in a few other cases written into the policy. With full tort, you keep the unrestricted right to claim, pain and suffering included. The limited tort discount isn't off your whole bill. It comes off the parts of the policy that pay for injuries: the liability coverage for injuring someone, your own medical benefits, and the two coverages for uninsured and underinsured drivers. There the state's rule is a discount of at least 40 percent, unless an insurer shows the state data that justify a different figure. The rule covers only those coverages, so the difference on your whole bill depends on what you carry. A good agent shows you both numbers side by side and lets you choose.
5. Who do I call with a claim, and what does your office do while it's open? Ask whether you'll call the agent's office or a company line, and what the office does while the claim is open. A good answer names a person you'll deal with and says what that person will do after you call; help with a claim is the praise fewest Berks reviews mention, so this is the question that separates the two agents.
6. Looking at what I have now, what would you add, what would you drop, and why? Bring the current policy. How the agent reads it is how every future renewal will feel.
What a good agent does for you at renewal.
A good agent reads the renewal with you, or calls before it's due. Every year your car insurer has to send an itemized invoice showing what the state-minimum coverages alone would cost, along with a notice of the two tort options. That invoice comes with your declarations, the page listing each coverage you carry and what it costs. The notice ends by saying that to change your tort option you have to notify your agent, broker or company and complete the form. Nothing changes unless you send that form.
One Fleetwood agency gives two more pieces of advice: talk to your agent so your policies are looked at together, and consult your agent before filing a small claim. Both need an agent who calls back.
How to switch car insurance without a coverage gap.
Our advice: start the new policy before the old one ends, even if the dates overlap by only a day. Ending the old policy is a call or a click to the old company, and the new agent will tell you the timing that avoids a gap. Once the old policy ends, the old company is required to tell PennDOT, whether you cancelled it or they did. Your new company isn't required to tell PennDOT you bought one. So PennDOT may assume you have no insurance and send you a proof letter. If one comes, don't panic, but answer it, by email to frinsurance@pa.gov or at dmv.pa.gov, or PennDOT will have to suspend your registration.
A suspension for a lapse runs three months. Once in any 12-month period, you can pay a $500 civil penalty instead of serving it. A lapse under 31 days is excused if the car wasn't driven.
The "easy to switch" compliment looks like this on one listing. CrossKeys Insurance in Reading has a review describing the agent explaining what needed to happen and what the options were without any hard sell, and another saying moving the policy was very easy.
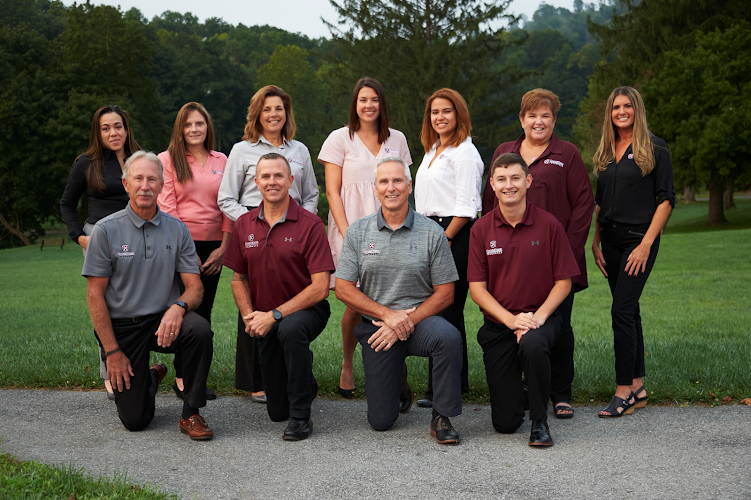
5035 Pottsville Pike, Reading, PA
If something goes wrong with an agent or a company along the way, the Insurance Department's Consumer Services line is 1-877-881-6388.
So here's tonight, with the renewal notice still on the counter. Pick two agents, run both names through the lookup, and book one conversation with each. Ask the six questions and notice who answers the phone. Then overlap the dates by a day and move.
Frequently asked questions.
How do I check whether an insurance agent is licensed in Pennsylvania?
Use the Pennsylvania Insurance Department's Licensed Individual Search with the agent's last name or city. It shows what they can sell and which companies they work with.
How many insurance agents should I talk to before I switch?
The state's advice is to compare at least three companies, not three agents. An independent agent may sell for many companies, so ask each agent how many they'd quote you; two agents can cover three companies if one of them does.
Can I switch car insurance in the middle of my policy without a gap?
Yes, if the new policy starts before the old one ends. PennDOT may send a proof letter anyway; answer it.
Where do I complain about an insurance agent in Pennsylvania?
Call the Insurance Department's Consumer Services line at 1-877-881-6388 or use its online portal, which covers companies, agents and public adjusters.
Sources
- Pennsylvania Insurance Department, "Continuing Education Requirements": the 24-hour requirement per two-year licensing cycle and the consequence of missing it.
- Pennsylvania General Assembly, The Insurance Department Act of 1921, Article VI-A (40 P.S. § 310.1 et seq.): the producer license (§ 601-A), continuing education (§ 608-A), the written fee agreement (§ 671-A), and the commercial-only fee rule and application-fee ban (§ 674-A).
- Pennsylvania Insurance Department, "Insurance Search Tool Library" and the Licensed Individual Search: what the individual and business entity lookups show and the last-name-or-city rule.
- Pennsylvania Insurance Department, "Find and Research Insurance Companies and Agents": the shopping advice, the compare-at-least-three-companies rule of thumb, and the Regulatory and Enforcement Action Search.
- Pennsylvania Insurance Department, Complaint Comparison Tool: that complaints alone do not indicate wrongdoing and should not be the sole basis for a choice.
- NAIC, "How to Choose an Insurance Agent" (February 1, 2019): the independent and captive definitions and that both receive a commission from the insurance company.
- Insurance Information Institute, "Background on: Buying Insurance": that the independent agent rather than the insurer legally owns access to policy renewals.
- BerksConnect directory, positive review themes on every active Berks County insurance agent listing, counted September 18, 2026 (121 insurance agent listings, 99 with themes, 501 positive themes; a listing counts in every group a positive theme name matches): the table, the order of what customers praise, and the specific compliments that repeat (quick, answered the phone, saved money, easy, explained, been with them for years).
- BerksConnect listing pages for DJI Insurance Agency and CrossKeys Insurance: the customer review quotes.
- 75 Pa.C.S. § 1791.1, "Disclosure of premium charges and tort options" and § 1705, "Election of tort options": the itemized invoice and tort notice at every renewal, the two options, and the full tort default.
- Pennsylvania Insurance Department, Notice 2003-07 (33 Pa.B. 4761, September 19, 2003): the required minimum 40% limited tort differential on four coverages.
- Blue Marsh Insurance, "Why did my home insurance bill increase?" and "Why the cost of insurance has gone up": the advice to coordinate policies with your agent and to consult the agent before filing a small claim.
- Pennsylvania Insurance Department, "You just changed Auto Insurance!! NOW WHAT?" (Rev. April 24, 2018): the PennDOT proof letter after a switch and how to answer it.
- 75 Pa.C.S. § 1786, "Required financial responsibility": the three-month registration suspension, the $500 civil penalty in lieu of it, and the under-31-day lapse exception.
- Pennsylvania Insurance Department, "Complaints, Questions, Help": the 1-877-881-6388 Consumer Services line and the online complaint portal.
- Pennsylvania Insurance Department, Consumer Services portal FAQ: that the portal takes complaints against an insurance company, insurance producer (agent/broker), or public adjuster.